The short answer
Most UK app banks want every director to live in the UK, so a UK company run from abroad needs a provider that publishes a different rule. On Finzil's data in October 2026, the best fits are:
- Tide for a free UK sort code;
- WorldFirst for clients paying in several currencies;
- iFAST Global Bank for FSCS-protected deposits;
- OMG One for directors in countries other providers refuse.
7 of the 13 providers on Finzil that only take UK companies refuse directors who live abroad. 8 providers give a UK company its own UK account details and accept directors living outside the UK.
How we picked
We started from the 298 provider profiles on Finzil, built from each provider's own eligibility pages, price lists and terms and checked between 8 and 23 October 2026. An account qualifies only if the provider publishes two things. It opens accounts for UK companies whose directors live outside the UK, and the company gets UK account details in its own name. Each pick answers one need, for a reason the provider publishes. Nobody paid to be listed, and Finzil doesn't rate providers.
Most UK app banks want every director in the UK
A UK limited company takes a day to form from anywhere in the world. The bank account is where it stops. Finzil has 13 providers that only accept UK-registered companies. Seven of them state that directors living abroad can't open an account, one more needs the director who applies to live in the UK, and two accept directors abroad.
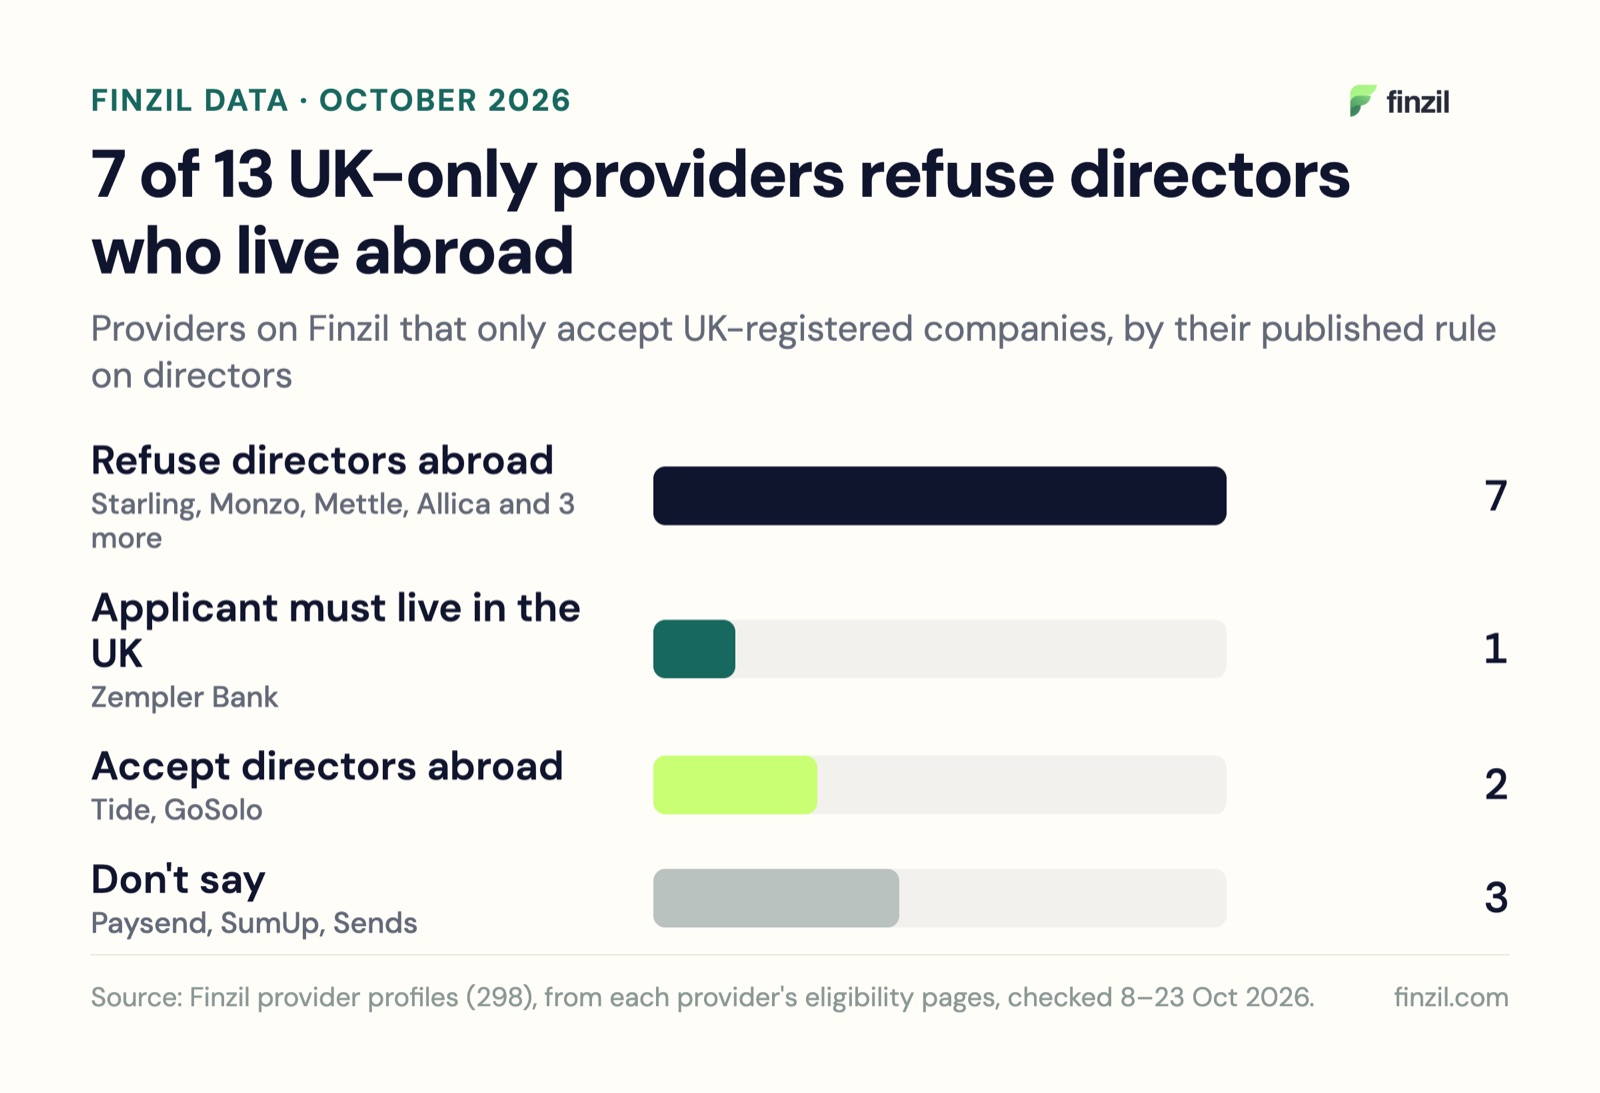
The wording varies; the effect doesn't. Starling Bank needs all owners and directors to live in the UK. Monzo Business needs you to be in the UK when you apply. HSBC UK needs the person applying to be a UK tax resident. Zempler Bank takes other directors from 36 listed countries, but the one who applies must live in the UK.
Lists of "UK banks for non-residents" online still include Starling and Monzo. Their own eligibility pages say otherwise.
The rule comes from what a bank has to check. Under the UK's money laundering rules, a bank must verify who you are and where you live before it opens the account. For a director in Leeds it can check a credit file and the electoral roll. For a director in Lagos it needs foreign documents, often a person to review them, and a view on the country. Our reading: a free account can't pay for a manual check, so the app banks that sell free accounts write directors abroad out of their rules.
The FCA's numbers show business applications are turned down more often than personal ones. In its review of account access, covering July 2022 to June 2023, the middle half of firms declined 0.2% to 11.4% of business applications. For personal accounts the range was 0.1% to 6.7% (FCA). The reasons firms gave most often were suspected financial crime and due diligence concerns.
Companies House now checks your directors before the bank does
Every director of a UK company has to verify their identity with Companies House, wherever they live. The rule started on 18 November 2025 with a 12-month transition, so existing directors have until 18 November 2026 (GOV.UK). By 11 June 2026, nearly 4 million people had verified, of the 6 to 7 million Companies House expects (Companies House).
It is harder from abroad. Companies House estimated that 117,639 people already on the register live overseas and hold the nationality of one of 112 countries whose passports the GOV.UK app can't read (Companies House equality assessment). They have to pay an Authorised Corporate Service Provider to verify them instead.
The bank account depends on it because providers read the register. One unverified director blocks the company's confirmation statement. The statement goes overdue, and the overdue filing is on the public record when a provider checks the company. The routes are in the Companies House ID check for directors abroad.
Our view: verify every director before applying for any account. It is the cheapest fix on this page.
A "UK account" can mean three different things
Ask a provider for a UK account and you can get any of these:
- A UK sort code and account number in your company's name. UK customers pay you by Faster Payments in seconds. This is what UK clients, payroll and HMRC expect.
- A GB IBAN in your company's name. The same thing in the international format: a GB IBAN contains a sort code and an account number. OMG One and Transferra describe their accounts this way.
- Pounds held on a foreign IBAN. Satchel gives a European IBAN and Dukascopy Bank Swiss IBANs in 24 currencies. Neither lists Faster Payments, so a UK customer paying you sends an international transfer, with its fee and its delay.
Rule of thumb: ask for the sort code. If the provider can't give one in the company's name, your UK customers will be making an international payment.
FSCS covers bank deposits; e-money is safeguarded instead
If a UK bank fails, the Financial Services Compensation Scheme pays back eligible deposits up to £120,000 per customer per banking licence, the limit since 1 December 2025 (FSCS). An e-money institution (EMI: licensed to hold and move your money, but not a bank) isn't covered. It must keep customers' money apart from its own. If the EMI fails, that money comes back through an administrator, which takes time and can cost something. Is my money safe at an EMI explains how.
Most accounts open to directors abroad are EMIs. On Finzil's data, one FSCS-protected bank account accepts a UK company whose directors all live outside the UK: iFAST Global Bank, a UK bank authorised by the PRA. Tide is partly there: its accounts provided by ClearBank are FSCS-protected, its e-money accounts are safeguarded. Revolut Business is a UK bank too, but it needs one director or owner living in the UK, the EEA or Switzerland.
Our view: for most small companies the bigger risk is an account closed or frozen, not a provider failing. Run day-to-day payments wherever the account works. Keep a reserve above a few months of costs at a bank with FSCS cover. Keep a second account open, because with one account a single closure stops every payment.
Best UK business accounts for non-resident directors, by need
| Best for | Account | First year | Why, on its published rules |
|---|---|---|---|
| A free UK sort code | Tide | £0 | Directors of UK companies may live overseas; free plan; needs a UK mobile number and a UK app store account |
| Clients paying in several currencies | WorldFirst | £0 | Non-residents accepted; receiving accounts in 22 currencies, sort code and account number for pounds |
| FSCS-protected deposits | iFAST Global Bank | £60 | UK bank, FSCS up to £120,000; 8 currencies under one account number; for companies under £7 million turnover |
| Directors in countries others refuse | OMG One | £49 | Directors from over 160 countries; GB IBAN in the company's name; no cards yet |
| A one-person company | GoSolo | £499 | Founders in 40 listed countries outside the UK; pounds only |
| Directors in the EU, paid in euros and pounds | Fire | £120 | Irish IBAN and UK sort code; directors in the EU or UK, others on request |
| Higher-risk or high-volume companies | Emerald24 or Transferra | £990 / €588 | Publish prices for owners abroad; 21 and 40+ currencies; both refuse US companies and owners |
| A relationship manager and local IBANs | 3S Money | €1,700 | UK sort code on Faster Payments, Bacs and CHAPS; 57 currencies; one to two weeks to open |
"First year" is the opening fee plus twelve months on the cheapest plan that accepts directors abroad, before payment and exchange fees.
Tide is where most directors abroad can start, and the condition people miss is the phone: Tide needs a UK mobile number and a phone registered to a UK app store.
The table leaves out a few costs. WorldFirst charges up to 0.5% to exchange (0.3% for the first six months), and some of its receiving accounts are in WorldFirst's or Alipay's name rather than yours. iFAST Global Bank waives its £5 monthly fee above a £10,000 average balance, charges £100 to open unless you onboard digitally, and £25 for each CHAPS or SWIFT payment. OMG One adds a balance charge of 0.05% to 0.5% depending on the plan. GoSolo takes founders living in the EU, the US, Canada, Australia, Hong Kong, Singapore, New Zealand or Ukraine, and the company must have one director who is also the only shareholder.
Two look like fits but aren't, for a company run entirely from abroad. Revolut Business needs one director or owner in the UK, EEA or Switzerland, plus a physical presence in the UK or EEA. Zempler Bank needs the applicant to live in the UK. If Revolut has already said no, the Revolut Business alternatives are sorted by the reason it gave.
The first year costs from nothing to €1,700
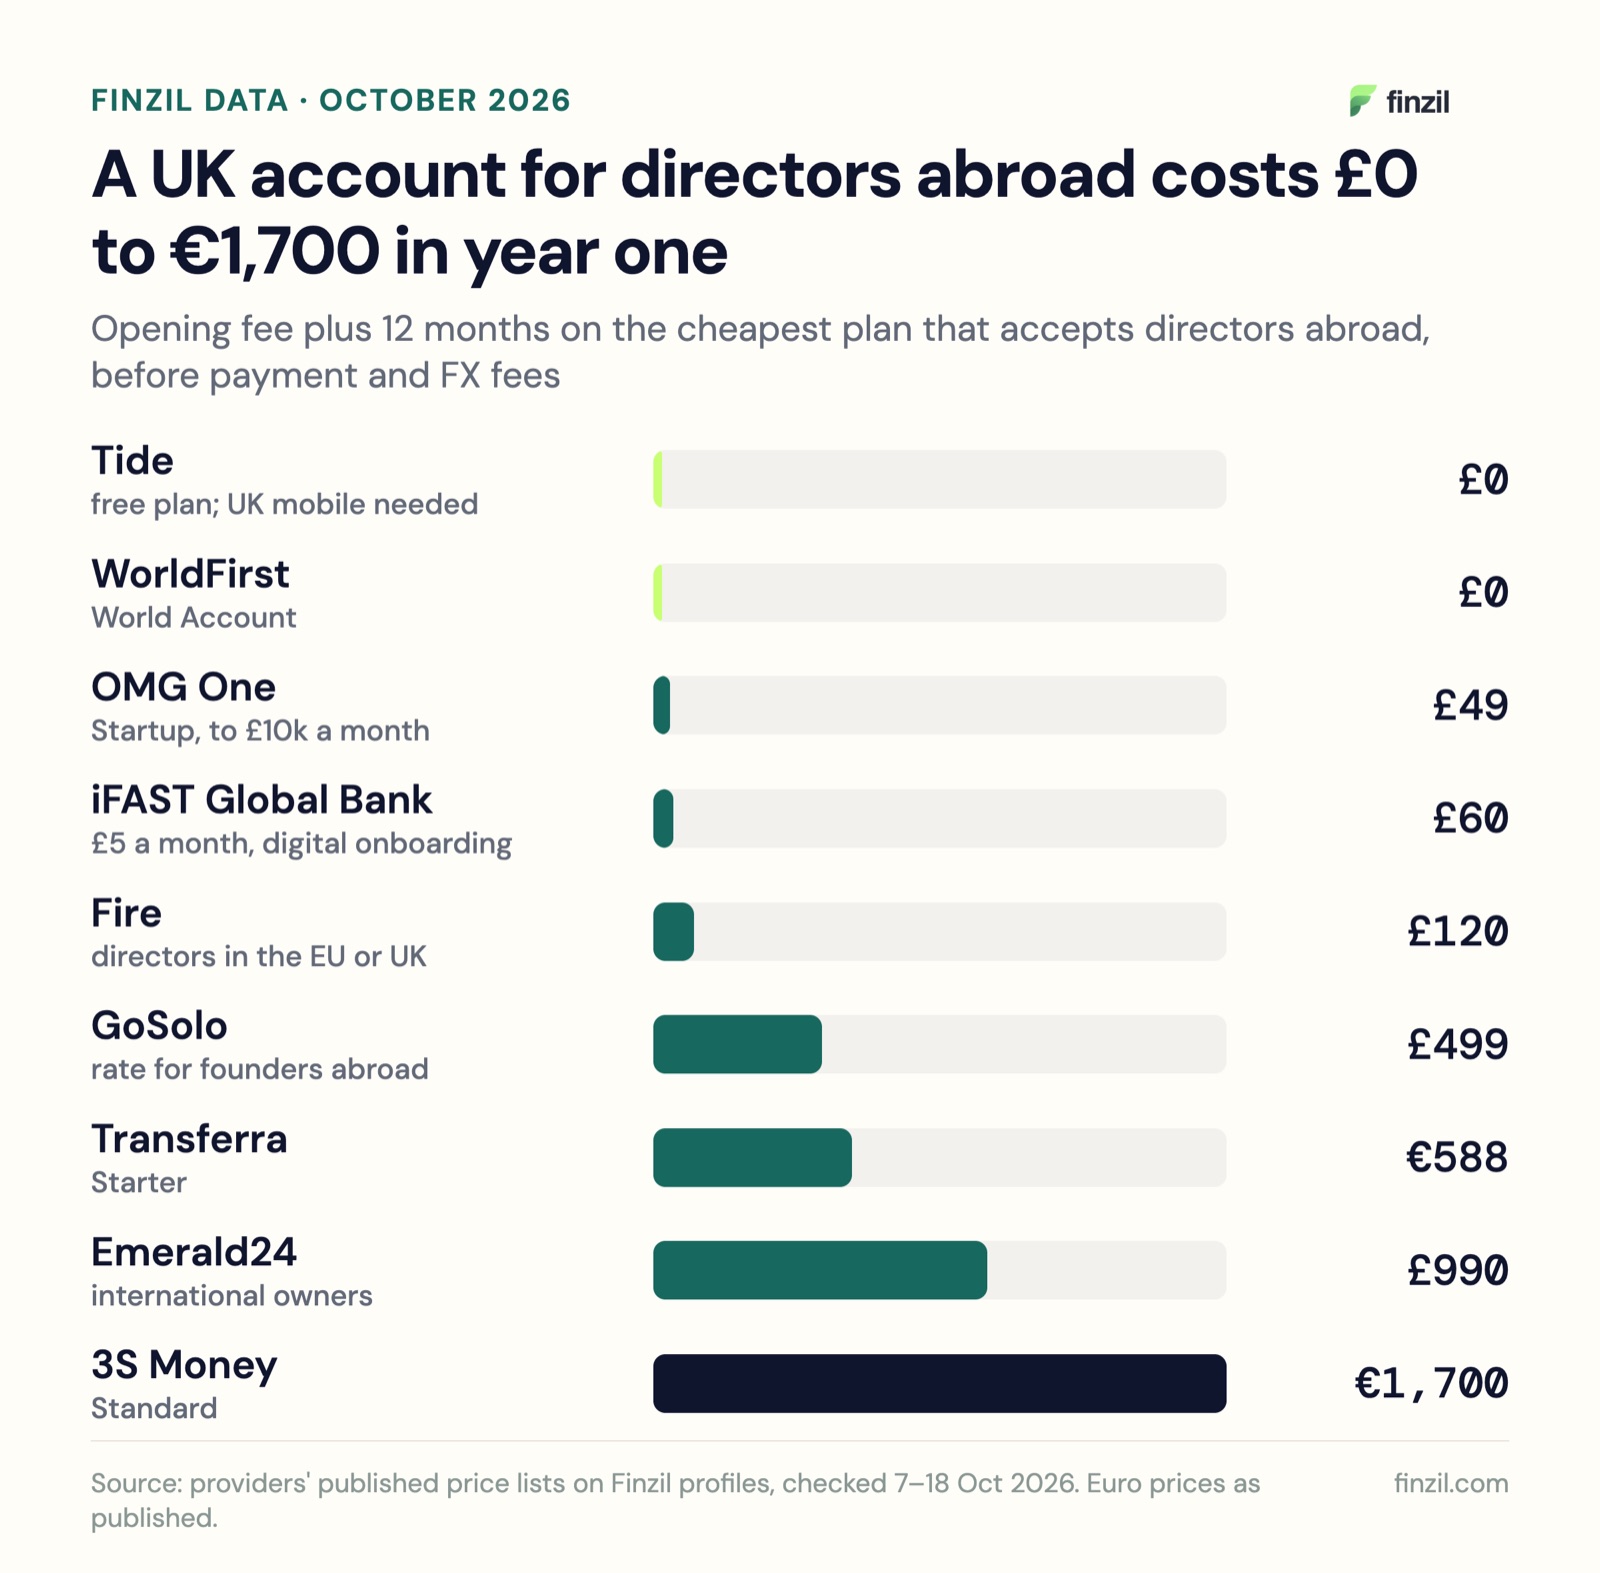
The gap pays for different things. Emerald24 charges £45 a month and £450 to open when owners live outside the UK, against £25 and £180 for local owners. That extra is the cost of checking foreign owners, priced openly. 3S Money charges €100 a month, €500 to open and €500 to close, for an account with a relationship manager. GoSolo is free for UK residents and £499 for the first year for founders abroad.
Our view: a higher price doesn't buy a better chance of approval. Start with a free account that accepts your directors' countries and gives a sort code in the company's name. Keep the paid ones for when a free one says no, or when your volumes or currencies outgrow it.
What to do
- Verify every director and PSC at Companies House before 18 November 2026, and check the company's filings are up to date on the register.
- Write down three facts: where each director and owner lives, what the company sells, and which currencies customers pay in.
- Shortlist accounts whose published rules accept all three and that give a sort code or GB IBAN in the company's name.
- Have the papers ready: certificate of incorporation, articles, the register of directors and shareholders, passport and proof of address for each director and each owner of 25% or more, and a short description of the business with proof it trades (contracts, invoices, a website).
- Apply to two at once, not one after another, and keep both if both say yes.
Matching step 2 against every provider's rules by hand is the slow part. Finzil runs that check across 298 providers. For the application itself, read opening a business account as a non-resident; if you've already been refused, read why business account applications get rejected.
Questions people ask
Can a non-resident director open a UK business bank account?
Yes, but not at most UK app banks. Tide, WorldFirst, iFAST Global Bank, OMG One, GoSolo, Emerald24, Transferra and 3S Money state that they accept UK companies whose directors live abroad and give UK account details (Finzil, October 2026).
Does Starling or Monzo accept non-resident directors?
No. Starling Bank needs all owners and directors to live in the UK, and Monzo Business needs the applicant to be in the UK when applying (published eligibility rules, October 2026).
Which UK business account with FSCS protection accepts directors abroad?
iFAST Global Bank, a PRA-authorised UK bank, accepts non-resident directors and protects eligible deposits up to £120,000 (Finzil, October 2026). Tide's accounts provided by ClearBank are also FSCS-protected; its e-money accounts are safeguarded instead.
Do I need a UK address to open a UK business account?
The company needs a UK registered office, which every UK company must have. The directors can live abroad at providers that accept non-residents, such as Tide, WorldFirst and OMG One, though Tide asks for a UK mobile number.
Does Companies House ID verification affect my bank account?
Yes, indirectly. An unverified director stops the company filing its confirmation statement, and providers check the register when you apply and when they review your account. Existing directors must verify by 18 November 2026.
Provider facts come from each provider's published eligibility pages, price lists and terms, recorded on 298 Finzil profiles checked between 8 and 23 October 2026. Outside figures: FCA, UK Payment Accounts: access and closures; Companies House and GOV.UK, read 3 November 2026; FSCS. Finzil doesn't rate providers and nobody paid to appear here. General information, not financial or legal advice.
Providers in this article
UK accounts that accept directors abroad
Each of these publishes that it opens accounts for UK companies whose directors live outside the UK. Check the director countries and industries on each profile before applying.
| Provider | Licensed in | Known for |
|---|---|---|
 TideE-money institution |  | Free planNon-residents accepted |
 WorldFirstE-money institution |  | Marketplace sellersTrade payments |
 iFAST Global BankBank | | Multi-currencyInternational companies |
 OMG.oneE-money institution | | Non-residents accepted37 currencies |
 GoSoloBusiness account platform | | Free accountNon-residents |
 FirePayment institution |  | EUR and GBPAPI |
 Emerald24E-money institution |  | UK local railsNon-residents accepted |
 TransferraE-money institution | | Non-residents accepted40+ currencies |
 3S MoneyE-money institution |  | Local IBANsNon-residents accepted |
Not sure which one fits? Your profile ranks them for your business, with the reason behind each.